Historical report: BlockBeats published this account on November 11, 2026, at 12:03 p.m. China time. It reproduces an investment argument by Starkiller Capital, which disclosed that it held the trade discussed below.
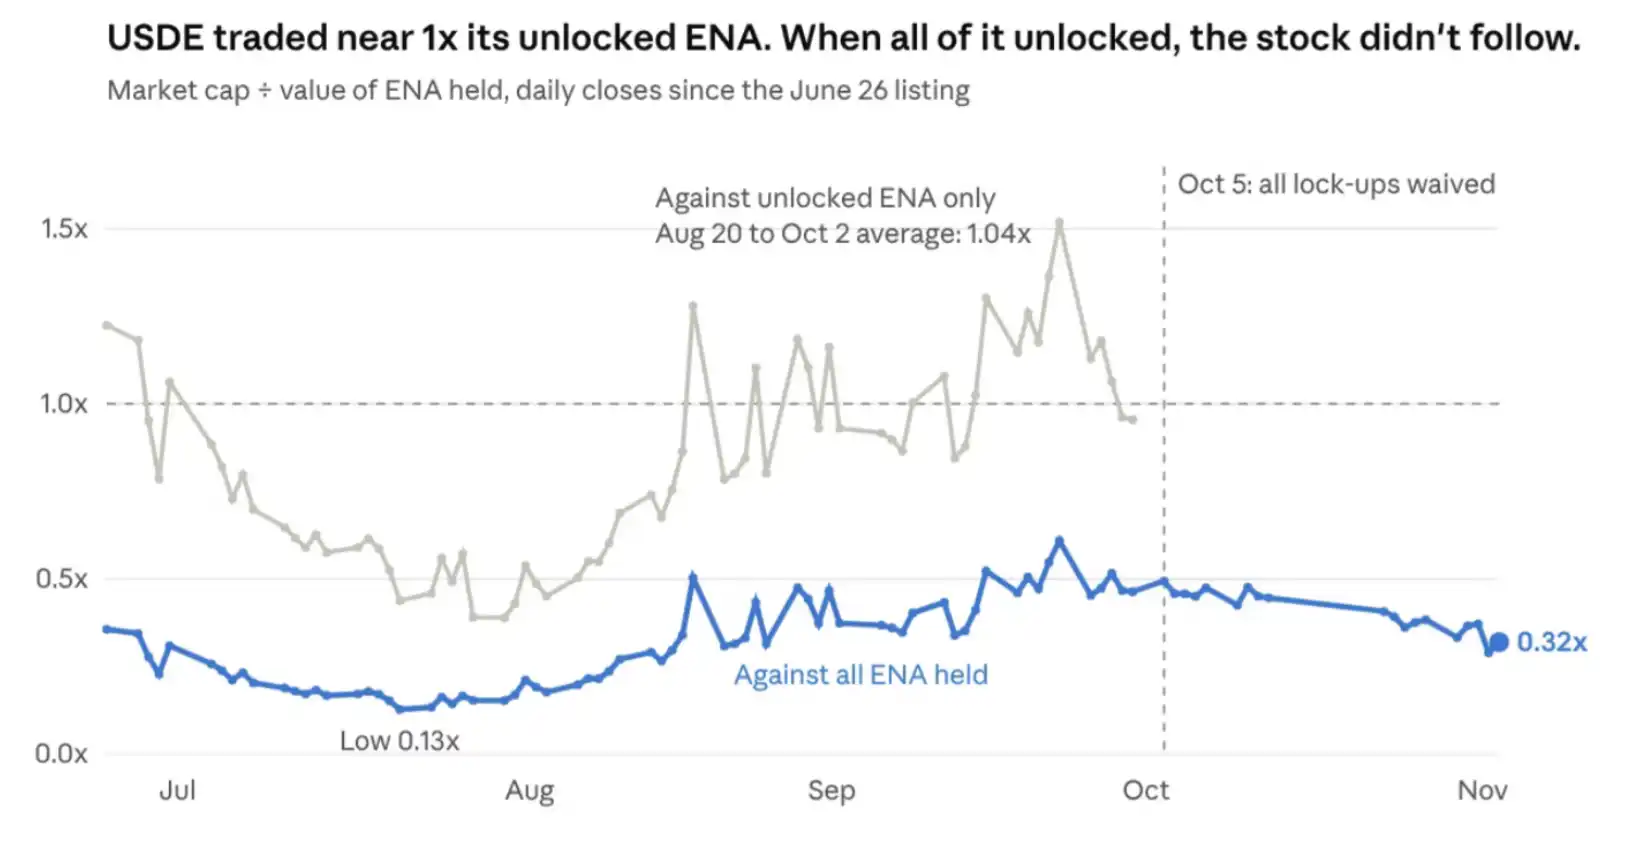
StablecoinX (Nasdaq: USDE) held 3.029 billion ENA tokens, according to Starkiller. At the preceding Friday’s close, its $6.43 share price compared with an estimated $20.10 of ENA per share, or 125.48 tokens. Starkiller put the company’s equity value at $155 million and its ENA holdings at $485 million. On its measure—market capitalization divided by the market value of ENA held—the stock traded at approximately 0.32× mNAV.
That ratio describes a discount, not a realizable profit. StablecoinX had no mechanism allowing shareholders to redeem shares for the underlying tokens. Its small infrastructure business, cash and liabilities also mean the ENA-only ratio is a simplified measure rather than a full valuation of the company. Starkiller reported $62,000 of infrastructure revenue for the final two weeks of June and, at the end of the second quarter, approximately $19 million in cash and $18 million in liabilities.
Why Starkiller considers the discount actionable
StablecoinX listed in June through a merger with SPAC TLGY. Under its token purchase agreement, roughly half its ENA was originally scheduled to vest over 48 months, with full unlocking in 2029; token sales also required Ethena Foundation consent. Starkiller said 1.56 billion ENA remained locked as of October 4. A letter signed by Ethena and the foundation on September 14 waived the lockup restrictions effective October 5. The letter also provided for certain financing sales, including sales to fund share repurchases under a foundation-approved 10b5-1 plan. An available, conditional route to repurchases is not an announced repurchase program. Token sales still require foundation approval.
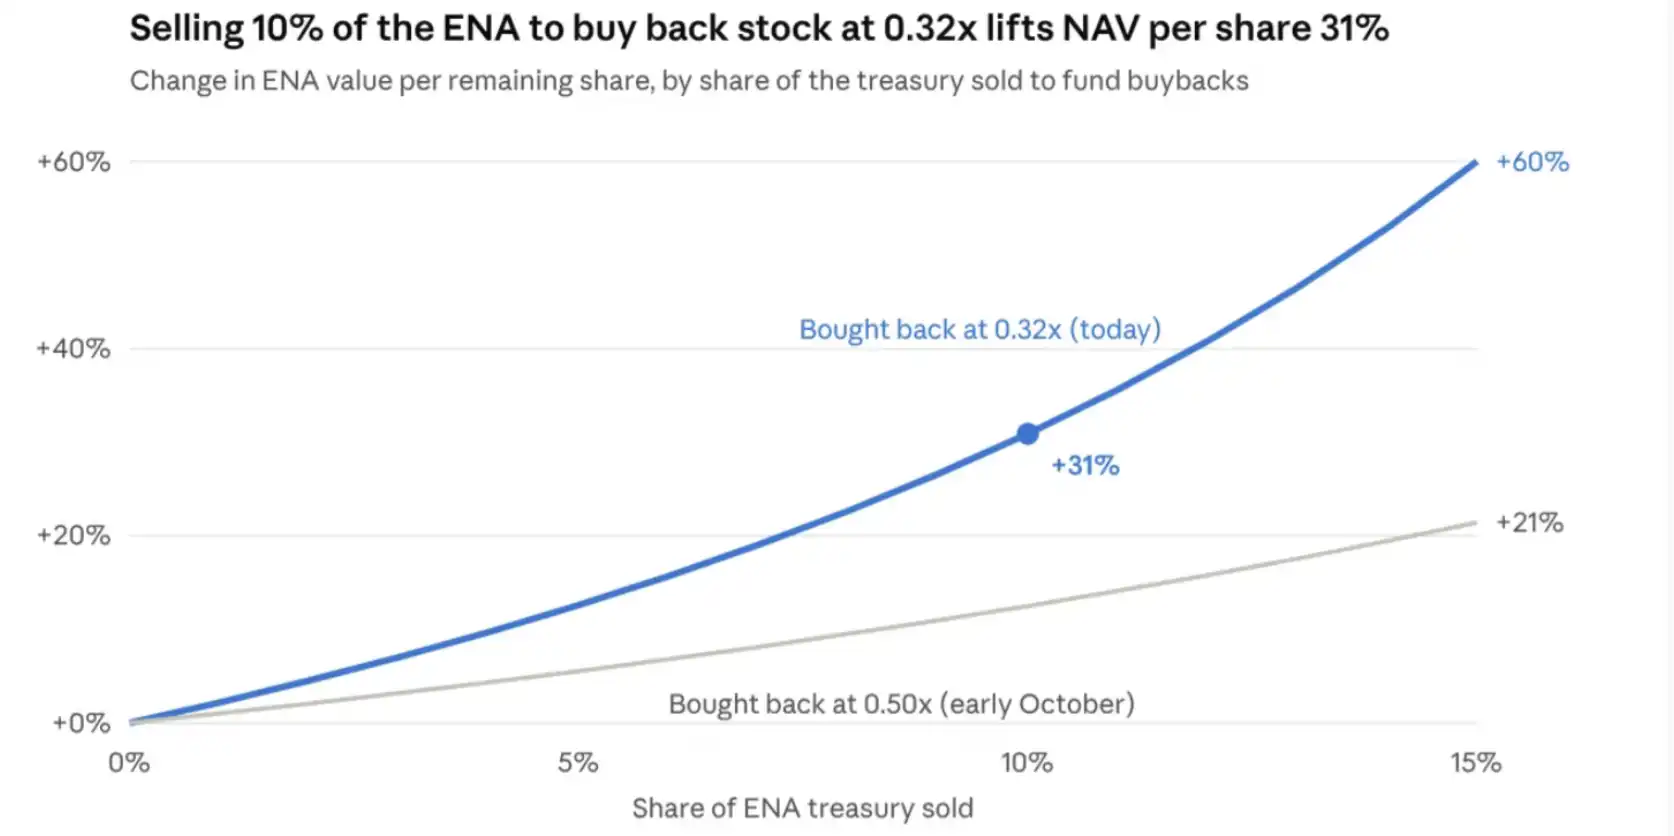
Starkiller’s proposed mechanism is per-share accretion: at 0.32× mNAV, selling $1 of ENA could, at unchanged prices, fund repurchases of shares representing about $3.13 of ENA holdings. Fewer tokens would remain, but the share count could fall faster. This arithmetic does not establish that the company will sell tokens, secure approval, repurchase shares at that price or eliminate the discount.
Starkiller said it bought shares in August at roughly 0.18× mNAV, took profits on an accumulated position around 0.60×, then rebuilt a larger position as the ratio fell. Its account also reports a rise from 0.15× to 0.61× during August and September. The November reading of 0.32× was therefore not a historical low. Starkiller attributed the renewed decline partly to the broader crypto-market sell-off and selling pressure in the less-liquid stock; those are its explanations, not proof of what caused the price move.
The trade and its limits
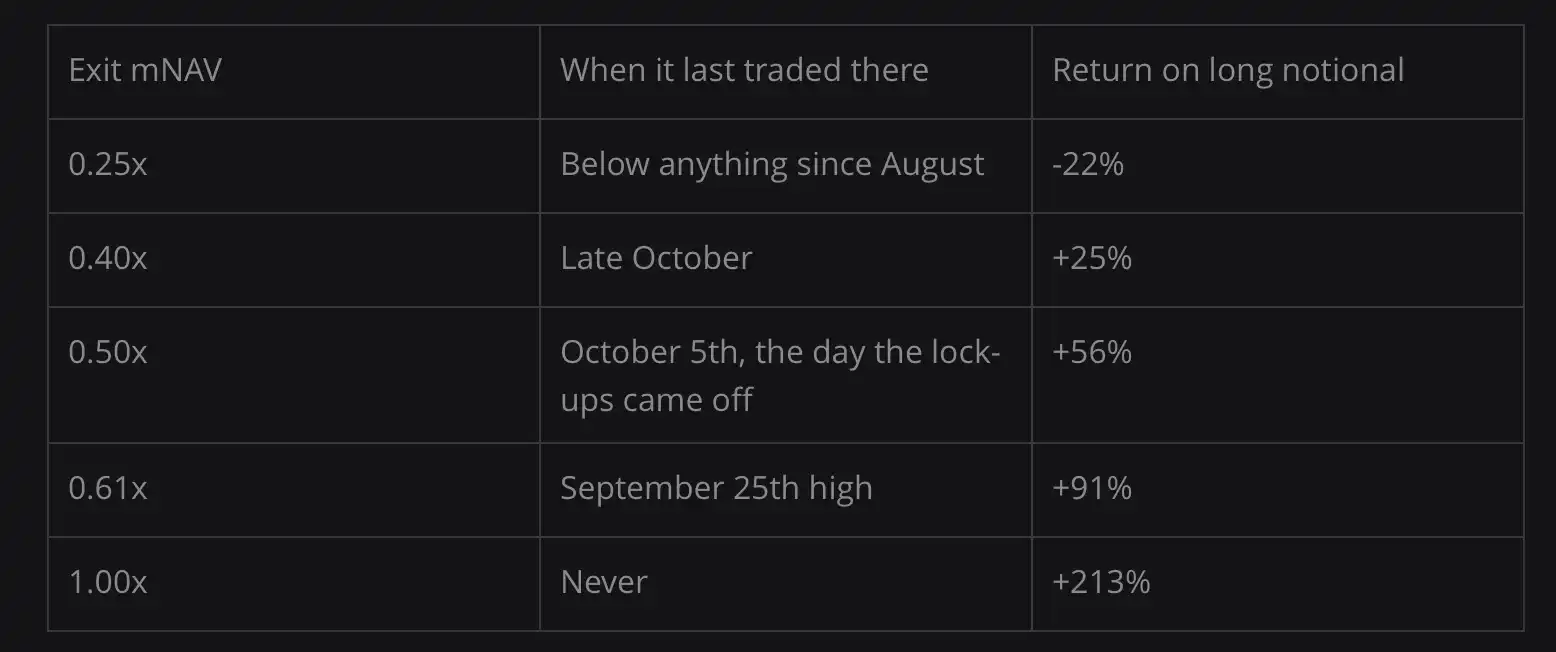
Starkiller described buying USDE shares while shorting an equal dollar amount of ENA, rather than shorting all 125.48 tokens attributed to each share. Its thesis is that the stock will outperform ENA as mNAV rises. The hedge does not remove changes in the valuation multiple, funding costs, trading costs or the need to rebalance. Starkiller said it used ENA perpetual futures and had received positive funding on its short, but future funding was not assured. Its estimated 56% gain on the long side if the ratio returned to its unlocking-day level assumed an unchanged ENA price and excluded funding and trading costs; it was not a forecast of net trade returns.
The decisive limitation is that nothing compels the discount to close. Starkiller identified foundation approval, potential resale of about 12.7 million registered shares, possible warrant dilution and further market declines as risks. It also noted that mNAV had fallen as low as 0.13× in July. At publication, Starkiller was watching for details of any repurchase plan in the third-quarter 10-Q, which it expected by November 16. The supplied account does not establish that such a plan was subsequently announced or executed.