Historical analysis: Published October 29, 2026, at 21:26 (UTC+8). Glassnode’s underlying price, order-book and hourly on-chain data ran through October 27; some daily on-chain, ETF and Hyperliquid measures ran through October 25 or 26. Recent daily observations could be revised.
Bitcoin was trading in a narrow range when Glassnode assessed whether demand could absorb supply above $84,000–$85,000. Its evidence pointed in both directions: ETF inflows had largely reversed and buying was uneven across wallet sizes, while realized losses on successive pullbacks had diminished. These are measures of market positioning, not a valuation model or a fair-value estimate.
Demand and holder costs
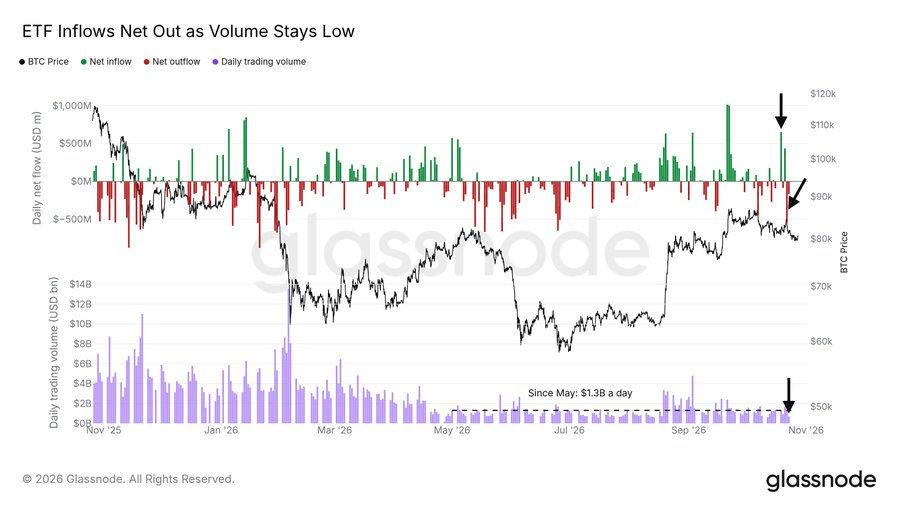
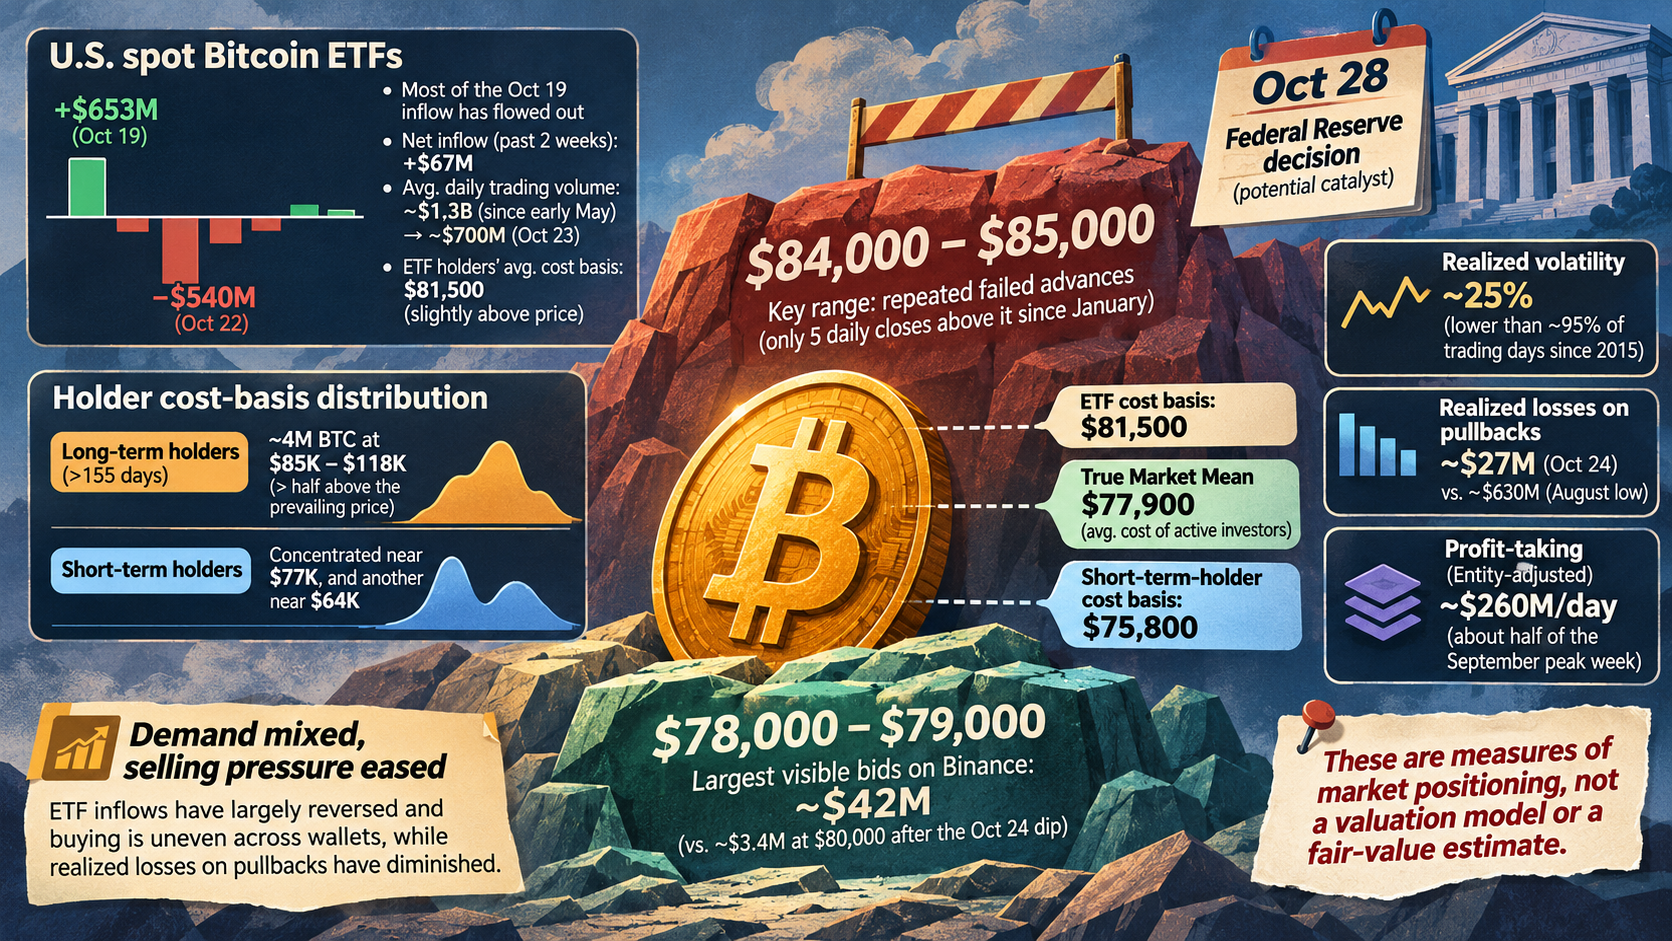
Glassnode reported that most of the $653 million that entered U.S. spot Bitcoin ETFs on October 19 had subsequently flowed out, including $540 million on October 22. Net inflows over the preceding two weeks were just $67 million. Average daily ETF trading volume had been about $1.3 billion since early May, falling to roughly $700 million on October 23. The report placed ETF holders’ average cost basis at $81,500, slightly above the prevailing price.
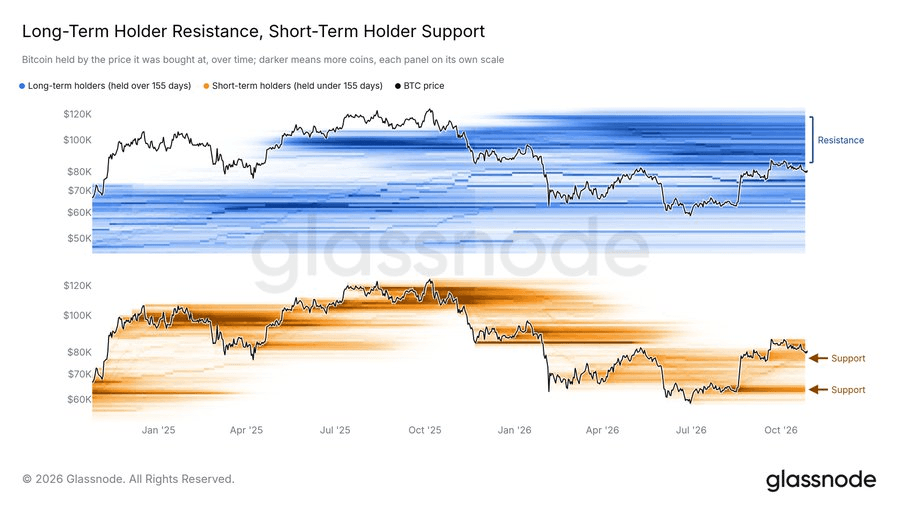
Glassnode’s cost-basis distribution groups bitcoin by the price at which it last moved. On that measure, long-term holders—those holding for more than 155 days—held about 4 million BTC with costs between $85,000 and $118,000. More than half of those coins had cost bases above the prevailing price. That creates potential selling pressure on a rebound, but the distribution alone cannot establish whether holders will sell. Short-term-holder supply was most concentrated near $77,000, with another concentration near $64,000.
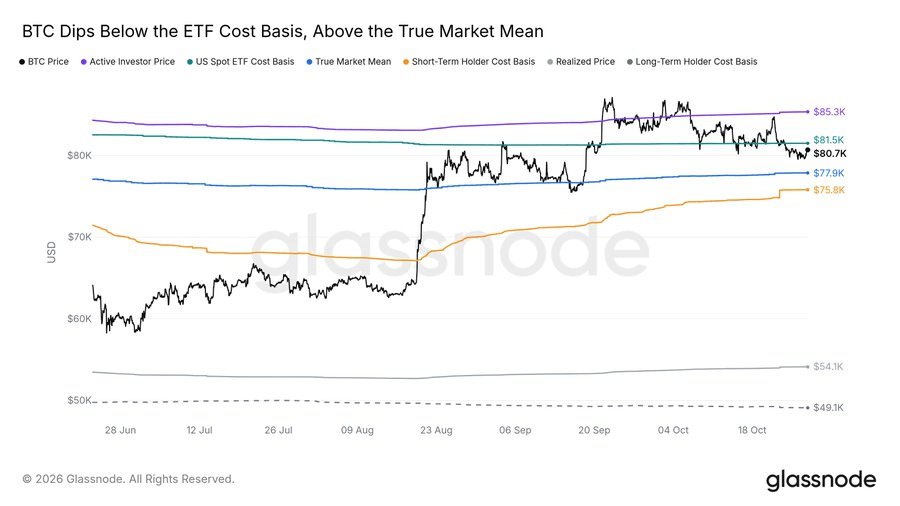
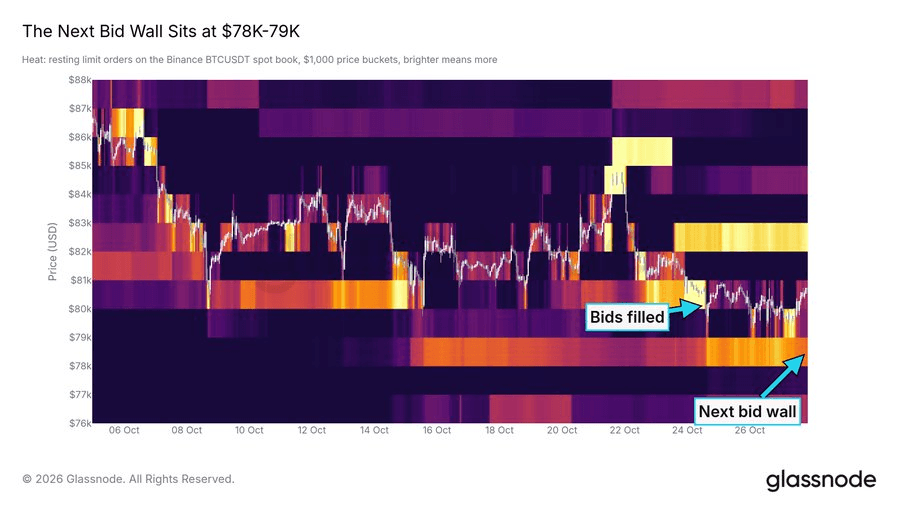
The report placed the True Market Mean, described as the average cost of active investors, at $77,900 and the short-term-holder cost basis at $75,800. These are distinct measures of historical acquisition costs, not guaranteed support levels. On Binance’s spot order book, Glassnode observed about $42 million in bids at $78,000–$79,000, versus $3.4 million remaining at $80,000 after an October 24 price dip. Visible orders can change or be withdrawn.
Why $84,000–$85,000 mattered
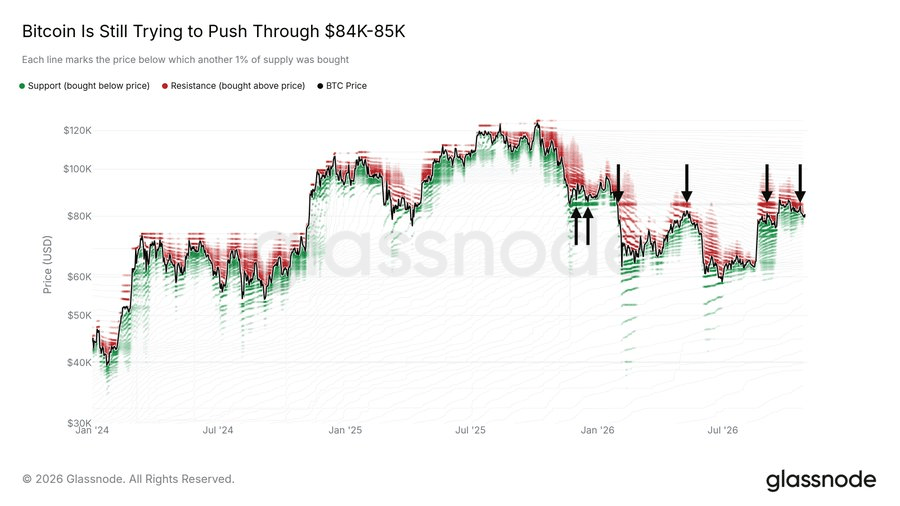
Glassnode said roughly 4.3% of Bitcoin supply last moved on-chain between $84,000 and $85,000. It cautioned that much of that activity came from a single large entity moving coins between its own wallets on November 22, 2025—not necessarily purchases at those prices. The report also identified repeated failed advances through the range. Since a January break below it, daily closes had exceeded the band on only five days, never for more than three consecutive days. Glassnode treated sustained daily closes above $85,000 as a first step toward reclaiming it, while its stronger demand test required a daily close above $87,500 alongside sustained ETF inflows and higher volume.
What the other indicators did—and did not—show
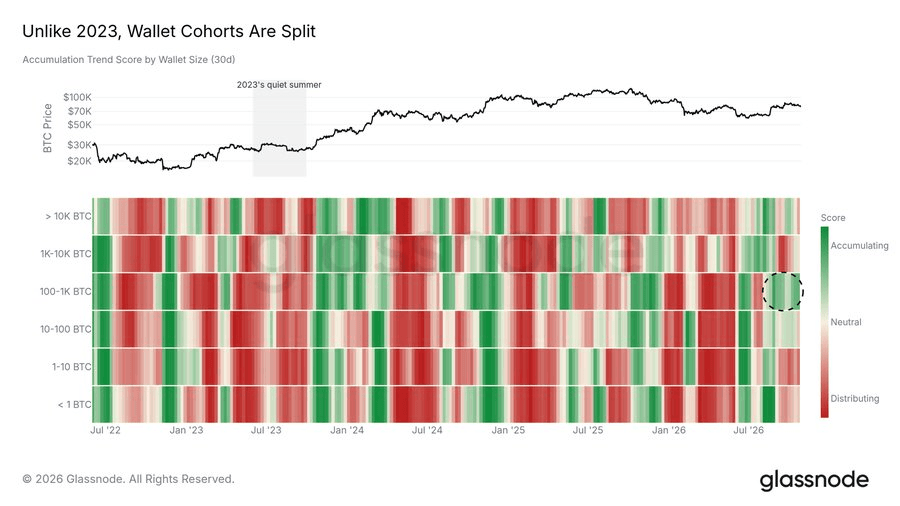
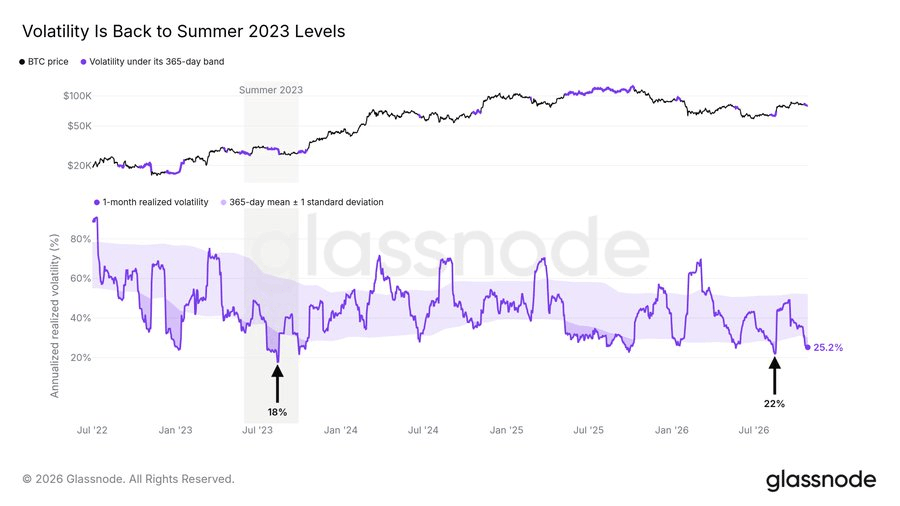
Glassnode’s accumulation trend score showed wallets holding 100–1,000 BTC as the strongest buyers that month; other cohorts’ behavior was mixed. One-month annualized realized volatility was about 25%, a level the report said Bitcoin had been below on only around 5% of trading days since 2015. Low realized volatility describes recent price movement; it does not determine the direction of the next move.
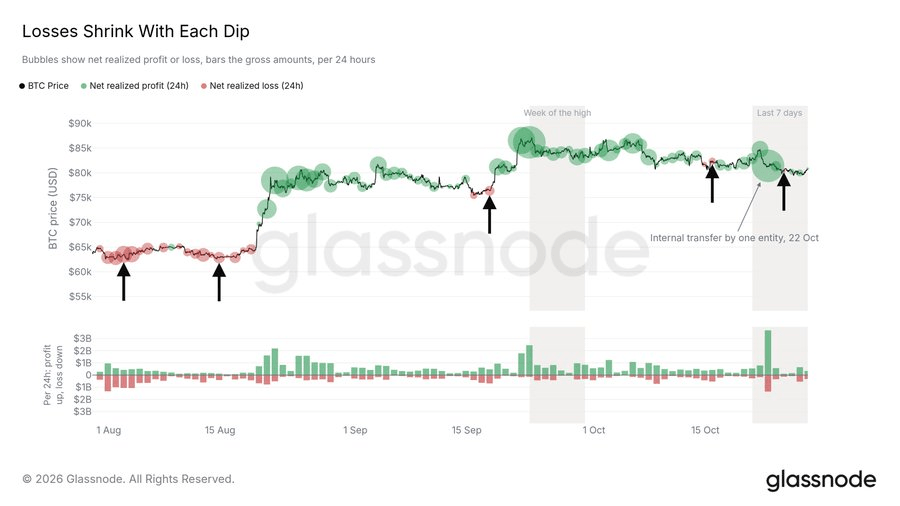
The report said the largest daily net realized loss on the October 24 pullback was about $27 million, compared with roughly $630 million at an August low. It also flagged an important measurement limit: one entity’s internal wallet transfers on October 22 added about $3.7 billion in realized profit and $1.4 billion in realized loss under standard on-chain accounting, without constituting market sales. After entity adjustment, Glassnode estimated profit-taking that week at about $260 million per day, around half the September peak week’s level.
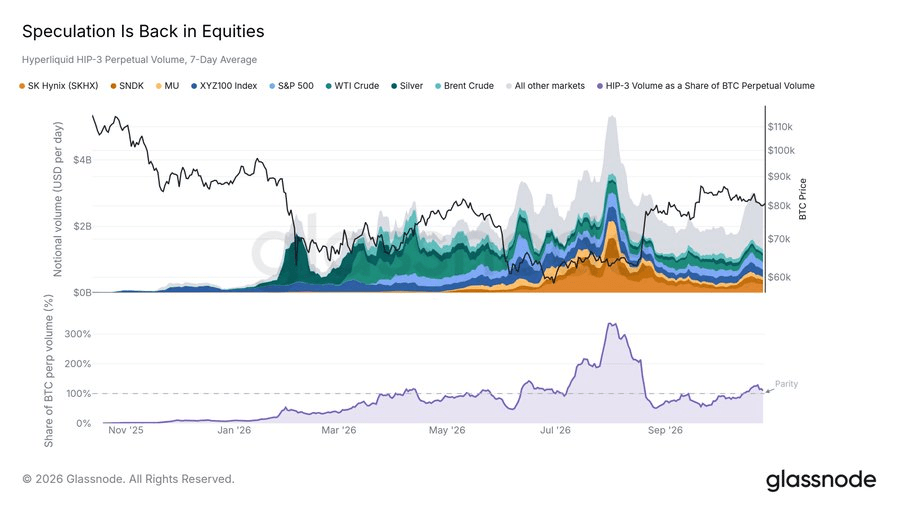
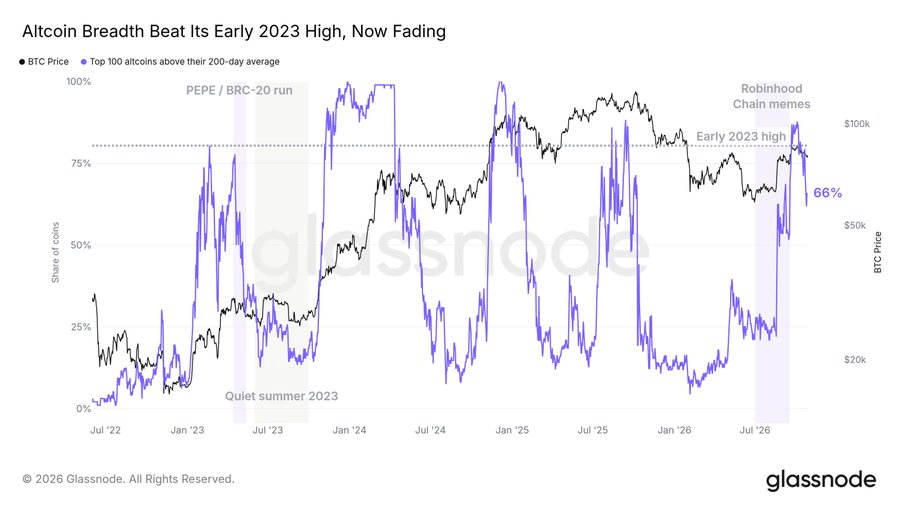
Outside Bitcoin, Glassnode cited Hyperliquid public data showing roughly $2.6 billion in average daily volume over the preceding week for its HIP-3 stock, index and commodity perpetual markets, versus about $2.4 billion for Bitcoin perpetuals on the same platform. Among the 100 largest altcoins, the share trading above its 200-day moving average had fallen from 88% on October 4 to 66%; the corresponding share among the top 500 was 42%. Those figures describe trading activity and market breadth, not protocol revenue or value accruing to token holders.
The report framed the October 28 Federal Reserve decision as a prospective catalyst in analysis based largely on data through October 27. Because this article was published on October 29, that framing should not be read as an update on the decision or its aftermath. The central observation remains narrower: demand indicators were weak, but measured selling pressure had also eased, leaving Glassnode focused on whether price could reclaim the upper cost-basis range or lose the $77,900 True Market Mean.
Source: hellobtc.com (originally published 2026-10-29 21:26 UTC+8)